<!-- Google tag (gtag.js) --> <script async src="https://www.googletagmanager.com/gtag/js?id=G-FNVKYB7G4T"></script> <script> window.dataLayer = window.dataLayer || []; function gtag(){dataLayer.push(arguments);} gtag('js', new Date()); gtag('config', 'G-FNVKYB7G4T'); </script>

Every parent wants to provide their child with quality education and a financially secure future. However, increasing school fees, university tuition, accommodation, and international education expenses can make this goal challenging. Planning early can help families manage these responsibilities without putting unnecessary pressure on their finances. A child education savings plan UAE provides a structured way to prepare for future academic expenses through regular savings and suitable investment options. Whether you are planning for school education in Dubai or a university abroad, building an education fund today can help you support your child’s ambitions tomorrow.
Table of Contents
What Is a Child Education Savings Plan UAE?
A child education savings plan is a financial strategy designed to help parents accumulate money for their children’s future educational expenses. It involves saving or investing a fixed amount regularly to meet future school, college, or university costs.
For families living in the UAE, education planning is particularly important because private schooling, international universities, accommodation, and additional academic expenses can require considerable financial preparation.
A suitable plan considers your child’s current age, expected education costs, monthly savings capacity, investment period, and financial risk tolerance.
The objective is simple: build a dedicated education fund gradually instead of depending entirely on your future income or borrowing money when university expenses arise.
Why Should Parents Start Saving for Their Child’s Education Early?
Starting early gives parents more time to prepare financially. Instead of arranging a large amount when their child reaches university age, they can distribute the responsibility across several years.
Here are four important reasons to begin early.
1. Prepare for Increasing Education Costs
School and university expenses can change over time. Tuition fees, books, transportation, technology, accommodation, and other academic requirements can increase the total education budget.
Regular savings help parents prepare for these expenses without disturbing their other financial priorities.
2. Benefit from Potential Investment Growth
Long-term investments may provide opportunities for capital growth, depending on the selected financial product and market conditions.
For example, certain diversified mutual funds allow investors to participate in different markets and investment sectors. However, returns are not guaranteed, and market-linked investments can lose value.
3. Reduce Future Financial Pressure
Having a dedicated education fund can reduce the need to depend on personal loans, credit cards, or emergency savings when your child enters higher education.
It also allows parents to manage their household budget more confidently.
4. Support International Education Opportunities
Many UAE families consider universities in the UK, USA, Canada, and Australia.
International education involves more than tuition fees. Parents should also consider accommodation, travel, visa expenses, health insurance, and everyday living costs.
Planning these expenses early can make international education goals more manageable.
7 Smart Strategies for a Child Education Savings Plan UAE
Choosing the right financial approach depends on your family’s circumstances, investment experience, and the number of years remaining before your child starts higher education.
Here are seven strategies worth considering.
1. Start a Monthly Savings Plan
Regular monthly savings are one of the simplest ways to build financial discipline.
Decide how much you can comfortably save after considering household expenses, insurance premiums, emergency savings, and other financial responsibilities.
For example, saving AED 500 every month means contributing AED 6,000 annually. Over several years, these contributions can create a meaningful education fund without requiring a large initial investment.
Practical tip: Start with an affordable amount and gradually increase your contribution whenever your income improves.
2. Explore Mutual Fund Investments
Mutual funds allow investors to participate in professionally managed portfolios containing different financial assets.
Depending on the fund, investments may include equities, bonds, money market instruments, or a combination of asset classes.
For parents with a longer investment horizon, diversified equity funds may offer growth potential. However, their values can fluctuate according to market conditions.
Before investing, consider:
- Investment objectives and duration.
- Historical performance and associated risks.
- Management fees and other charges.
- Portfolio diversification.
- Your ability to tolerate market fluctuations.
Choose mutual funds according to your financial goals rather than relying only on past performance.
3. Consider Fixed Deposits
Fixed deposits can be suitable for parents who prefer predictable interest or profit arrangements.
You deposit a specific amount with a bank for an agreed period and receive returns according to the product’s terms.
They may be useful for money that you expect to need within a shorter period.
Compare interest or profit rates, minimum deposit requirements, withdrawal conditions, and early termination penalties before selecting a product.
4. Explore Child Education Insurance Plans
Some insurance providers offer savings-oriented products that combine life insurance protection with a long-term savings component.
Depending on the policy, these products may provide scheduled contributions, maturity benefits, or additional financial protection.
Before purchasing a policy, carefully review:
- Life insurance coverage.
- Premium payment requirements.
- Policy duration.
- Guaranteed and non-guaranteed benefits.
- Early withdrawal and surrender charges.
- Policy exclusions and conditions.
Understand the complete cost structure and benefits before making a long-term commitment.
5. Build a Diversified Investment Portfolio
A diversified portfolio spreads investments across different asset classes rather than concentrating all your money in one investment.
For example, a portfolio may include equities, bonds, and cash or money market investments.
Diversification can help manage concentration risk, although it cannot eliminate investment losses.
Parents with longer investment periods may consider growth-oriented investments. As university approaches, they can gradually review their allocation and consider reducing exposure to investments with significant short-term volatility.
6. Maintain a Separate Emergency Fund
Your child’s education savings should not become your family’s only financial reserve.
Unexpected expenses such as medical bills, employment changes, home repairs, or urgent travel can affect your monthly budget.
Maintain a separate emergency fund so that you do not need to withdraw long-term education investments at an unsuitable time.
A commonly used starting target is three to six months of essential household expenses, adjusted according to your family’s circumstances.
7. Review Your Savings Strategy Regularly
Your financial plan should change when your income, family circumstances, or education goals change.
Review your progress at least once a year.
Check whether your contributions are keeping pace with estimated education costs. Also review investment performance, fees, risk exposure, and the number of years remaining before the money is required.
Regular reviews help keep your education savings strategy aligned with your family’s changing needs.
Comparison of Education Savings and Investment Options in UAE
Different financial products serve different purposes. Understanding their features can help parents make informed decisions.
| Financial option | Main advantage | Risk level | Suitable purpose |
|---|---|---|---|
| Savings account | Easy access to money | Generally low | Short-term savings |
| Fixed deposit | Predetermined interest or profit terms | Generally low | Planned expenses |
| Mutual funds | Professional portfolio management | Varies by fund | Long-term goals |
| Education insurance | Savings with insurance protection | Depends on policy | Long-term planning |
| Diversified portfolio | Exposure to different assets | Depends on allocation | Wealth building |
| Money market funds | Short-term financial instruments | Generally lower than equity funds, but not risk-free | Short-term allocation |
Returns, fees, liquidity, and capital protection vary between products. Always review the official product documents before investing.
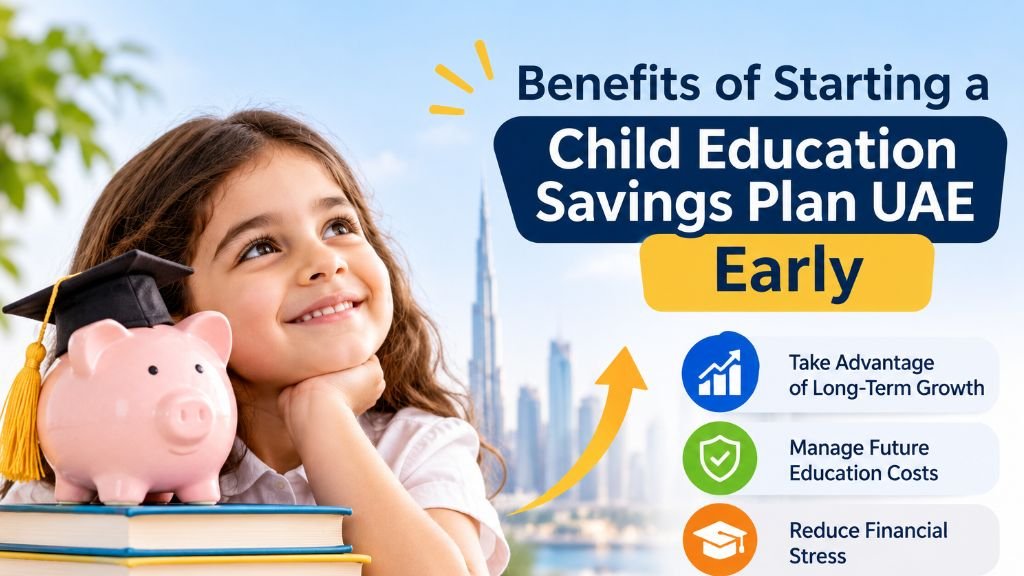
Benefits of Starting a Child Education Savings Plan UAE Early
Starting a child education savings plan UAE early gives parents more time to prepare for their children’s academic expenses. Regular monthly contributions can help build an education fund gradually without creating a major financial burden. Parents can also review different savings and investment opportunities according to their income, financial goals, and investment duration. Early planning provides greater flexibility when preparing for school fees, college tuition, and higher education expenses.
Child Education Savings Plan UAE for Expats and Working Families
For expatriate families living in Dubai, Abu Dhabi, and other UAE cities, planning children’s education is an important part of long-term financial management. A child education savings plan UAE can help working parents prepare for local schooling or international university expenses while managing their other financial commitments. Families should consider their expected stay in the UAE, future education destinations, currency requirements, and available savings options before selecting a suitable financial strategy.
Important Factors to Consider Before Investing in Education Savings
Before choosing an education savings product, parents should understand its investment objectives, associated charges, liquidity, and potential risks. A child education savings plan UAE should match the child’s age, expected university expenses, and the family’s financial capacity. It is also important to compare different financial products instead of selecting an option based only on advertised returns. Understanding the terms and conditions can help parents make informed decisions and avoid unexpected financial commitments.
How Regular Contributions Can Build a Strong Education Fund
Consistency plays an important role in achieving long-term financial goals. Parents who contribute a fixed amount every month can gradually develop a dedicated education fund. For example, setting aside AED 750 monthly means contributing AED 9,000 annually, excluding any potential investment growth. With a structured child education savings plan UAE, families can monitor their savings progress, increase contributions when their income improves, and prepare more effectively for future academic expenses.
Plan Your Child’s University Expenses with Professional Financial Guidance
University education can involve several expenses beyond tuition fees, including accommodation, travel, study materials, and daily living costs. Parents should estimate these expenses before deciding how much to save. A child education savings plan UAE can provide a structured starting point for preparing for these responsibilities. Bricks Consultancy helps individuals and families understand financial planning and explore investment considerations based on their long-term financial objectives. Professional guidance can help parents evaluate available options and develop a more organised approach towards their children’s educational future.
5 Steps to Choose the Right Education Savings Strategy
Before selecting a financial product, follow these five practical steps:
- Identify your education goals: Decide whether you are planning for local schooling, university education, or overseas studies.
- Estimate future expenses: Calculate tuition fees, accommodation, transportation, books, and other expected costs.
- Determine your investment period: Your child’s current age will help establish how much time you have to build the fund.
- Compare financial products: Review savings accounts, fixed deposits, insurance-linked plans, and investment opportunities based on their risks, charges, and flexibility.
- Monitor your progress: Review your contributions and financial strategy regularly to make sure you remain on track.
A professional financial assessment can help you understand which options align with your financial objectives and risk tolerance.
Why Choose a Child Education Savings Plan UAE for Long-Term Financial Security?
Choosing a child education savings plan UAE is an important step towards building a financially secure future for your children. With proper financial planning, parents can prepare for school fees, university tuition, and international education expenses without putting excessive pressure on their monthly income. A structured savings strategy also helps families maintain financial discipline, manage future expenses, and work towards their educational goals with greater confidence.
How to Make Your Child Education Savings Plan UAE More Effective?
To make your child education savings plan UAE more effective, start by setting a realistic education savings target based on your child’s age and future academic requirements. Consider monthly contributions, suitable investment options, potential education inflation, and the number of years available to save. Reviewing your financial strategy regularly can help you identify gaps, adjust contributions, and keep your education fund aligned with your long-term goals.
Secure Your Child’s Educational Future with Smart Financial Planning
A well-planned child education savings plan UAE can help parents prepare for important milestones, from primary school to higher education. Instead of waiting until university expenses arise, start building your education fund through consistent savings and carefully evaluated investment opportunities. With the right financial guidance, families in Dubai and across the UAE can make informed decisions, manage education-related expenses, and create better opportunities for their children’s future.
What Parents Say About Financial Planning
The following are illustrative testimonial examples, not verified customer reviews. Replace them with genuine, approved client feedback before publishing.
Testimonial 1
“Understanding different savings options helped us create a more organised approach towards our child’s future education expenses.”
Testimonial 2
“Having a clear financial goal made it easier for us to plan monthly contributions and stay focused on long-term savings.”
Testimonial 3
“Reviewing our financial priorities helped us understand how to balance family expenses with our children’s future education goals.”
Frequently Asked Questions (FAQs)
1. What is the best child education savings plan UAE?
The right plan depends on your financial goals, savings period, and risk tolerance. Parents can explore savings accounts, fixed deposits, mutual funds, and insurance-linked savings products before selecting a suitable strategy.
2. How much should I save monthly for my child’s education?
Your monthly savings amount depends on expected education expenses and the number of years available. Estimate your total target and divide it by the remaining saving months. Review your target regularly to account for inflation and changing costs.
3. Are mutual funds suitable for children’s education planning?
Mutual funds may be suitable for some long-term education goals because they provide access to professionally managed portfolios. However, they carry market risks, and returns are not guaranteed. Select funds according to your investment horizon and risk tolerance.
4. When should parents start saving for their child’s education?
Parents should ideally start as early as possible. Beginning when a child is young gives families more time to make regular contributions and potentially benefit from long-term investment growth.
5. Can UAE residents save for their children’s overseas education?
Yes. UAE residents can explore different savings and investment options for overseas education. They should also consider foreign currency requirements, exchange rate movements, tuition inflation, accommodation, and international living expenses.
Conclusion
Preparing for your child’s education is one of the most meaningful financial goals you can establish as a parent. Starting early, saving consistently, comparing financial products, and reviewing your progress can help you build a stronger foundation for future education expenses.
A child education savings plan UAE should reflect your family’s income, savings capacity, investment horizon, and educational ambitions. There is no single financial product that works for every family, so careful evaluation and professional guidance are important.
At Bricks Consultancy, we help individuals and families understand financial planning and explore suitable investment strategies for their long-term goals.
Start planning for your child’s brighter future today.